Whales are among the largest and most remarkable animals on Earth. These marine mammals live in oceans around the world, from warm tropical waters to the cold seas surrounding the poles.
Life Beneath the Surface
Although whales spend their lives in water, they breathe air through blowholes located on top of their heads. They must regularly return to the surface to breathe before diving again in search of food or traveling through the ocean.
Whales are warm-blooded, give birth to live young, and nurse their calves with milk. A thick layer of fat called blubber helps protect them from cold water and stores energy during long migrations.
Two Main Groups
Whales are generally divided into baleen whales and toothed whales. Baleen whales filter small animals from the water using flexible plates inside their mouths. This group includes blue whales, humpback whales, and gray whales.
Toothed whales use teeth to catch fish, squid, and other prey. Many of them also use echolocation, producing sounds and listening for returning echoes to understand their surroundings. Sperm whales, belugas, and orcas belong to this group.
The Blue Whale
The blue whale is the largest known animal to have ever lived. An adult can grow longer than a city bus and weigh well over one hundred tonnes. Despite its enormous size, it feeds mainly on tiny crustaceans called krill.
Communication and Migration
Whales communicate using clicks, whistles, pulses, and complex songs. Some sounds can travel across great distances underwater. Humpback whales are especially famous for their long, patterned songs.
Many species migrate thousands of kilometres each year. They often feed in cold, nutrient-rich waters before traveling to warmer regions where they mate and give birth.
Protecting Whales
Commercial hunting once caused severe declines in many whale populations. Today, whales also face threats from fishing gear, ship collisions, underwater noise, pollution, and changes to ocean ecosystems.
Conservation programs, safer fishing practices, protected habitats, and international cooperation can help whale populations recover. Protecting whales also supports healthier oceans because these animals play an important role in marine food webs and nutrient cycles.
The short-term rental tax loophole lets a property owner use rental losses to offset W-2 wages in the same year, without being a full-time real estate professional. It works because the IRS passive activity rules treat a rental where the average guest stay is 7 days or less as something other than a “rental activity.” If you also materially participate in running it, those losses count as non-passive and can reduce your active income, including your day-job salary. The large first-year loss usually comes from depreciation, sped up with a cost segregation study and bonus depreciation.
I have managed properties for owners who ran this play with their accountant, and the mechanics are not a secret or a gray-area trick. Every piece of it sits in published IRS guidance. Below is how the rule works, who it actually helps, and the parts most people skip, like recapture when you sell and the records the IRS expects you to keep.
This is general education, not tax advice. Tax rules change and depend on your situation. Consult a licensed CPA or tax professional before acting.
What the short-term rental “loophole” actually is
Start with the default rule. Rental real estate is normally a “passive” activity. Passive losses can only offset passive income, not your W-2 paycheck or your business profit. That is the wall most owners hit: they have a paper loss from depreciation, but the IRS will not let it touch their salary.
There is a well-known escape hatch called real estate professional status, but it is closed to most people with a job. The IRS says you have to spend more than half of all your working time in real property trades or businesses, and more than 750 hours a year in them, per IRS Publication 925. A full-time W-2 employee almost never clears that bar.
The short-term rental rule is a different door, and it does not require real estate professional status at all. That is the whole reason it gets called a loophole. It is not a loophole in the sense of a mistake in the law. It is a specific treatment the IRS wrote for short-stay rentals, and it has been on the books for years.
The 7-days-or-less test: why short stays are not a “rental activity”
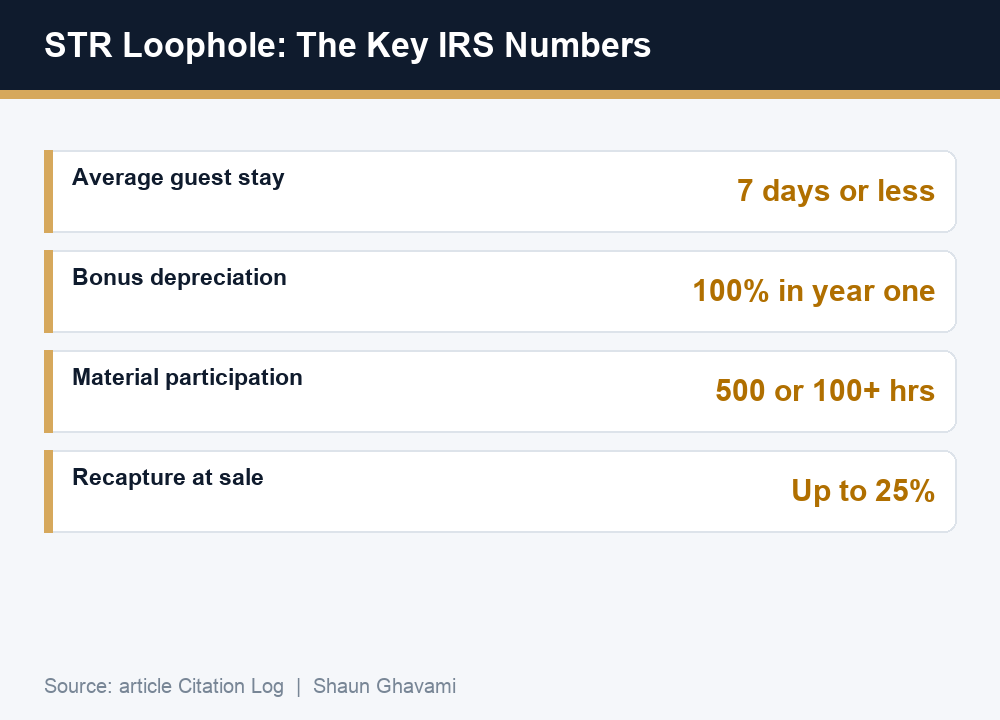
The passive activity regulations (Treasury Regulation 1.469-1T(e)(3)(ii)) list activities that are not counted as “rental activities.” The first one on that list, restated in Publication 925, is simple: “The average period of customer use of the property is 7 days or less.”
Read that carefully. It is the average stay across the year, not every single booking. A property that mostly takes weekend and few-night stays, the typical Airbnb pattern, usually lands under seven days on average. A traditional long-term rental with month-long or year-long tenants does not.
Why does this matter so much? Because once your activity is not a “rental activity,” it is treated like any other trade or business for the passive loss rules. And a trade or business you are involved in can produce non-passive losses. That is the pivot the whole strategy turns on. This is also why the type of hosting you do decides everything, a point I come back to below in who it works for.
Material participation: how the loss becomes non-passive
Clearing the 7-day test is only half of it. To make the loss non-passive and usable against your W-2 income, you also have to materially participate in the activity. The IRS defines material participation with a set of tests in Publication 925 (drawn from Temporary Regulation 1.469-5T). You only need to meet one of them for the year.
The ones short-term rental owners lean on most:
The 500-hour test: you participated in the activity for more than 500 hours during the year.
The “did almost all the work” test: your participation was substantially all the participation by anyone in the activity that year.
The 100-hour test: you participated for more than 100 hours, and at least as much as any other individual, including a cleaner or a co-host.
Time spent booking, guest communication, pricing, restocking, coordinating cleaners and repairs, and bookkeeping generally counts. Hiring a full-service property manager who does everything usually breaks material participation, because then someone else is doing more of the work than you are. If you want the deduction, you have to stay hands-on and log your hours. I keep a dated time record the same way I keep receipts, because the burden is on the taxpayer to prove it.
Want the operator’s version of this, not the textbook version? I walk through how real hosts structure ownership, hours, and cash flow inside the free class. Get the free Airbnb training.
Where the big first-year loss comes from: depreciation
The 7-day test and material participation only open the door. They do not create a loss by themselves. The loss comes from depreciation, and specifically from front-loading it.
Buildings normally depreciate slowly. The IRS depreciates residential rental property over 27.5 years under the schedule in IRS Publication 527 (short-stay properties used mostly on a transient basis can fall into a longer, nonresidential class instead, which is a detail for your CPA). Either way, spreading a building’s cost over decades produces a small yearly deduction, not a big one.
Two rules speed that up dramatically:
Cost segregation
A cost segregation study breaks the property into its parts. Instead of treating the whole building as one 27.5-year (or 39-year) asset, an engineer-based study reclassifies components like appliances, cabinets, flooring, and land improvements into much shorter recovery periods of 5, 7, and 15 years. The IRS Cost Segregation Audit Techniques Guide describes these studies as allocating the total cost of a property across its land, its building, and the appropriate depreciation asset classes. Shorter lives mean far more of the cost can be deducted early. I break the mechanics down further in our guide to cost segregation for short-term rentals.
Bonus depreciation
Bonus depreciation (the “additional first year depreciation deduction” under Internal Revenue Code Section 168(k)) lets you deduct a large share of qualifying shorter-life assets in the very first year instead of spreading them out. This is the highest-stakes number in the whole strategy, because the percentage has changed repeatedly with legislation. As of this writing, the One Big Beautiful Bill restored it: the IRS states the law “provides a permanent 100-percent additional first year depreciation deduction for qualified property acquired… after Jan. 19, 2025,” in its official guidance on the deduction (Notice 2026-11). Confirm the current percentage and the acquisition date rules with your CPA before you rely on them, because this is exactly the kind of figure that moves.
Put together, cost segregation identifies the shorter-life property, and bonus depreciation lets you write off a large chunk of it in year one. Both deductions are reported on IRS Form 4562. That combination is what produces a loss big enough to matter against a salary.
The four IRS-anchored numbers behind the short-term rental tax loophole. Figures verified against IRS.gov; see the Citation Log.
A worked example (illustrative only)
Here is how the pieces fit together with round numbers. Read the label first.
Illustrative example. Assumed inputs, not a promise. Your land and building split, your cost segregation results, your tax bracket, and your eligibility will all differ. This is a teaching example, not a projection of your outcome. Run your own numbers with a CPA.
Step
Assumed figure
Purchase price of the short-term rental
$500,000
Portion that is land (not depreciable)
$100,000
Depreciable building basis
$400,000
Share a cost seg study reclassifies to 5, 7, 15-year property
25% ($100,000)
Year-one bonus depreciation on that reclassified property
$100,000 (assumes 100% bonus)
Assumed marginal federal rate
32% (example only)
Approximate first-year federal tax reduction
about $32,000
The paper loss in this example is roughly the reclassified $100,000 (plus normal depreciation on the rest of the building and ordinary operating costs). If you meet the 7-day test and materially participate, that non-passive loss can offset up to that amount of your active income, including W-2 wages, in the same year. You did not spend $100,000 in cash that year, so a deduction that size against a salary is why owners pursue this. It is a timing benefit, and the next section is the part sellers wish they had read first.
Who it works for, and who it does not
This strategy only works for people who own the property. The entire benefit comes from depreciating an asset you own. No owned building, no depreciation, no loophole. That single fact rules out two of the most common ways people run Airbnbs.
Rental arbitrage hosts: if you lease an apartment and re-list it, you own nothing to depreciate. You can still deduct your real business costs, but there is no building basis to cost-segregate. Our rental arbitrage guide covers the model and its real tax picture.
Co-hosts: if you manage other people’s listings for a fee, the depreciation belongs to the owner, not to you. Co-hosting is a great cash-flow business, and I like it, but it does not generate this deduction. See our breakdown of co-hosting.
It works for owners who buy (or already hold) a short-stay property, keep the average guest stay at seven days or less, and stay involved enough to materially participate. If you are still deciding whether to buy at all, our guide on how to start an Airbnb business and the real Airbnb startup costs are the honest starting point, and market choice matters, so look at the most profitable Airbnb cities before you commit capital.
The caveats the sales pitches skip
Depreciation is not free money. It lowers your cost basis, and the IRS takes its share later. Here is what to plan for.
Depreciation recapture at sale
When you sell, the gain tied to depreciation you claimed gets recaptured. For the building portion, the IRS taxes unrecaptured Section 1250 gain “at a maximum 25% rate,” per IRS Topic 409. The shorter-life personal property from your cost seg study (Section 1245 property) is generally recaptured as ordinary income. That is why this is a deferral, not a permanent escape. Some owners defer it further with a 1031 exchange, but that has its own rules to check with your CPA.
Documentation and audit risk
Material participation and cost segregation are both areas the IRS looks at closely. You need contemporaneous time logs, and a cost seg study should be done by qualified professionals, not guessed at. Sloppy records are the fastest way to lose the deduction on audit.
It is not automatic, and Schedule C is a trap
You have to qualify every year. If your average stay creeps above seven days, or you hand the work to a manager and stop participating, the treatment changes. And if you provide hotel-level “substantial services,” the IRS may push your rental onto Schedule C, where profits face self-employment tax. Our comparison of Schedule E vs Schedule C for Airbnb walks through where that line sits. Beyond depreciation, keep clean books on the everyday write-offs too, our list of Airbnb tax deductions covers those.
None of this is a reason to avoid the strategy. It is a reason to run it with a professional. I do not file this on my own, and I would not want you to either. If you do not have someone yet, start with what to look for in an Airbnb tax accountant.
Ready to build the kind of portfolio this applies to? The free training shows how hosts get started, whether you own, arbitrage, or co-host. Get the free Airbnb training.
Frequently asked questions
Is the short-term rental tax loophole legal? Yes. It is a treatment written into the IRS passive activity rules, not a trick. A rental with an average guest stay of 7 days or less is not a “rental activity” under Publication 925, so if you materially participate, the losses can be non-passive. It is general education here, not tax advice, so confirm your situation with a CPA.
Do I have to be a real estate professional to use it? No, and that is the point. Real estate professional status requires more than half of your working time and over 750 hours a year in real property businesses, which most W-2 earners cannot meet. The short-term rental rule instead relies on the 7-day average stay plus material participation, per IRS Publication 925.
Does this work for rental arbitrage or co-hosting? No. The benefit comes from depreciating a building you own. If you lease and re-rent (arbitrage) or manage other people’s listings (co-hosting), you own no property to depreciate, so there is no first-year loss to offset your W-2 income. You can still deduct your ordinary business expenses.
What is the average 7-day rule exactly? IRS Publication 925 lists activities that are not “rental activities.” The first is when “the average period of customer use of the property is 7 days or less.” It is the average across the year, not every booking, which is why typical short-stay Airbnbs qualify and long-term leases do not.
Will I owe the tax back when I sell? Largely, yes. Depreciation reduces your cost basis, so at sale the IRS recaptures it. Unrecaptured Section 1250 gain on the building is taxed at a maximum 25% rate per IRS Topic 409, and shorter-life cost seg property (Section 1245) is generally recaptured as ordinary income. Treat the deduction as a deferral, not free money.
Is this article tax advice? No. This is general education, not tax advice. Tax rules change and depend on your situation. Consult a licensed CPA or tax professional before acting on any of it.
AllTheRooms is the STR analytics platform you reach for when AirDNA
coverage thins. It aggregates listings across Airbnb, Vrbo, Booking.com, and other
platforms with international depth that AirDNA does not match. After the August 2025
acquisition by Deckard Technologies, the platform also gained the policy-data layer used
by municipalities and academic researchers.
Honest verdict. AllTheRooms wins for international portfolio investors and for any
operator looking at markets where AirDNA's listing count is thin. AirDNA wins for
U.S. address-level estimates and UI polish. The two tools answer different questions.
Our full AllTheRooms review covers the data source coverage,
the deduplication patents, the post-acquisition direction, and the operator profiles
this tool fits. If you are picking a state to operate in, the
best states for Airbnb ranks the states where we have seen
operators land successfully.
10XBNB students who use AllTheRooms treat the data as a flashlight, not a
decision-maker. Analytics show you the size and shape of demand; the operator system
turns that into a market choice, a deal, and a working unit. Live coaching, the active
community, and mentorship from operators with collectively about a thousand doors keep
the analytics in the right role.
Mashvisor occupies a different niche than AirDNA. It blends traditional
real estate data, MLS comps and zip-code level statistics, with short-term rental
analytics. The result is best for investors making buy-vs-rent decisions and dual-strategy
operators who need to compare long-term and short-term returns side by side.
Where it shines: investor underwriting that requires both sides of the equation,
because no pure STR tool answers the long-term comparison. Where it falls short: pure STR
markets where AirDNA still has cleaner data and deeper comp coverage.
Our full Mashvisor review runs the side by side with AirDNA,
covers the actual pricing across the four Mashvisor tiers, and is honest about data
accuracy issues in some markets. For city-level recommendations the
profitable Airbnb cities covers the markets where we have seen the
strongest cash-on-cash returns.
10XBNB students who use Mashvisor treat it as a supplement, not a replacement for
AirDNA. The buy-side analytics inform the long-term hold scenario; AirDNA informs the
STR scenario; the operator system on top of both is what turns the data into a real
acquisition decision. Live coaching, the active community, and mentorship from
operators who have run both strategies make the comparison productive instead of
theoretical.
AirDNA is the gold standard for short-term rental market data. Most
serious investors and operators reference it at some point. The honest question, which
most reviews avoid, is where the data is reliable and where it drifts.
Reliable: mature urban and suburban markets with hundreds of comparable listings.
Phoenix, Nashville, Orlando, Austin. AirDNA reads pickup pace, ADR, and occupancy with
high confidence in these markets. Less reliable: rural markets, emerging vacation
markets, and any city where the active-listings count is under fifty. The model is
honest about confidence intervals, but readers often miss the caveats.
Our full AirDNA review for Airbnb investors walks through the Rentalizer
tier (free with paid lookups) versus MarketMinder (paid subscription), how the methodology
actually works, and the gotchas around cleaning-fee inflation and monthly refresh lag.
If you are using AirDNA to pick a market, also read
best Airbnb markets in 2026 for our take on the markets that actually
work in 2026.
10XBNB students use AirDNA inside a five-step market validation workflow. Free
Rentalizer to screen, MarketMinder on the short list, cross-checks with local property
managers, a conservative discount against the projection, and only then a lease.
Live coaching, the active community of operators across many markets, and mentorship
from operators with collectively about a thousand doors keep students from over-trusting
any single data source.
Hostaway is the rising mid-market PMS. It sits in the gap between
Hospitable (best for one to fifty listings, guest-comm first) and Guesty (best for
enterprise and property management companies). For operators with five to fifty listings
who need more channel depth than Hospitable offers, Hostaway is increasingly the right
answer.
The reason is the marketplace. Hostaway integrates with hundreds of partner tools
including Pricelabs, Stessa, OwnerRez, Stripe, and just about every major STR tool
you would name. That depth turns Hostaway into a true operator hub. The flip side is
that some integrations are paid add-ons, which the marketing pages do not call out.
Our full Hostaway review covers the marketplace breadth,
the channel manager strength, and the operator profiles Hostaway actually fits. For the
broader channel manager landscape, the
Airbnb channel manager guide ranks the major options including
Hostaway, Hospitable, Guesty, Lodgify, and OwnerRez.
10XBNB students who run Hostaway use the marketplace to connect the PMS to their
pricing tool, their bookkeeping, their smart locks, and their cleaning team. Live
coaching, the active student community, and mentorship from operators with about a
thousand collective doors help students set up the right integrations in the right
order without paying for tools they will not use.
Guesty is built for property management companies and operators with ten
or more listings. For a one to three listing arbitrage operator, it is overkill and the
pricing reflects that. The right question is when Guesty actually becomes the right pick.
The signal is usually simple. You are managing multiple owners, handling trust
accounting, syncing with more than three booking channels, or running a co-hosting
business at scale. That is the Guesty zone. Below it, Hospitable or Hostaway typically
serve the same operator better and cheaper.
Our full Guesty PMS review walks through Guesty for Hosts
(the smaller-scale tier) vs Guesty Pro (the enterprise product), the actual pricing
behavior at different portfolio sizes, and where the learning curve hits hardest. If
you are exploring the path from operator to co-host to property manager, the
co-hosting business covers what that transition looks like.
10XBNB students who scale into Guesty are usually past the point where coaching is
optional. The platform handles trust accounting, owner statements, and multi-channel
sync, which means the operator now has to know how to use those features without
breaking anything. Live coaching, the active student community, and mentorship from
operators who have made the same scale jump make the difference between Guesty being a
force multiplier and an expensive paperweight.